THE DAILY PULSE Bonds got some relief on Thursday. The AI trade did not.The S&P 500 fell 0.46% to about 7,766. The Nasdaq lost 1.25%. The Dow rose 52 points, or 0.1%, and the Russell 2000 ended flat. The 30-year yield rose to about 5.70% early, just below Wednesday's 24-year high. Long yields turned lower around midday, when President Trump posted on Iran. They held lower through the 1 p.m. bond sale. The 10-year ended near 5.23%, down about 5 basis points. Brent reached $105.91, then eased after his post ruled out a strike on Iran before the midterms. It still ended the stock session up about 3.4%, near $103.60. Bitcoin dipped below $81,000 for the first time since Sept. 21. Borrowing got a little cheaper. The payoff for AI looked a little less sure. PREMIER FEATURE 
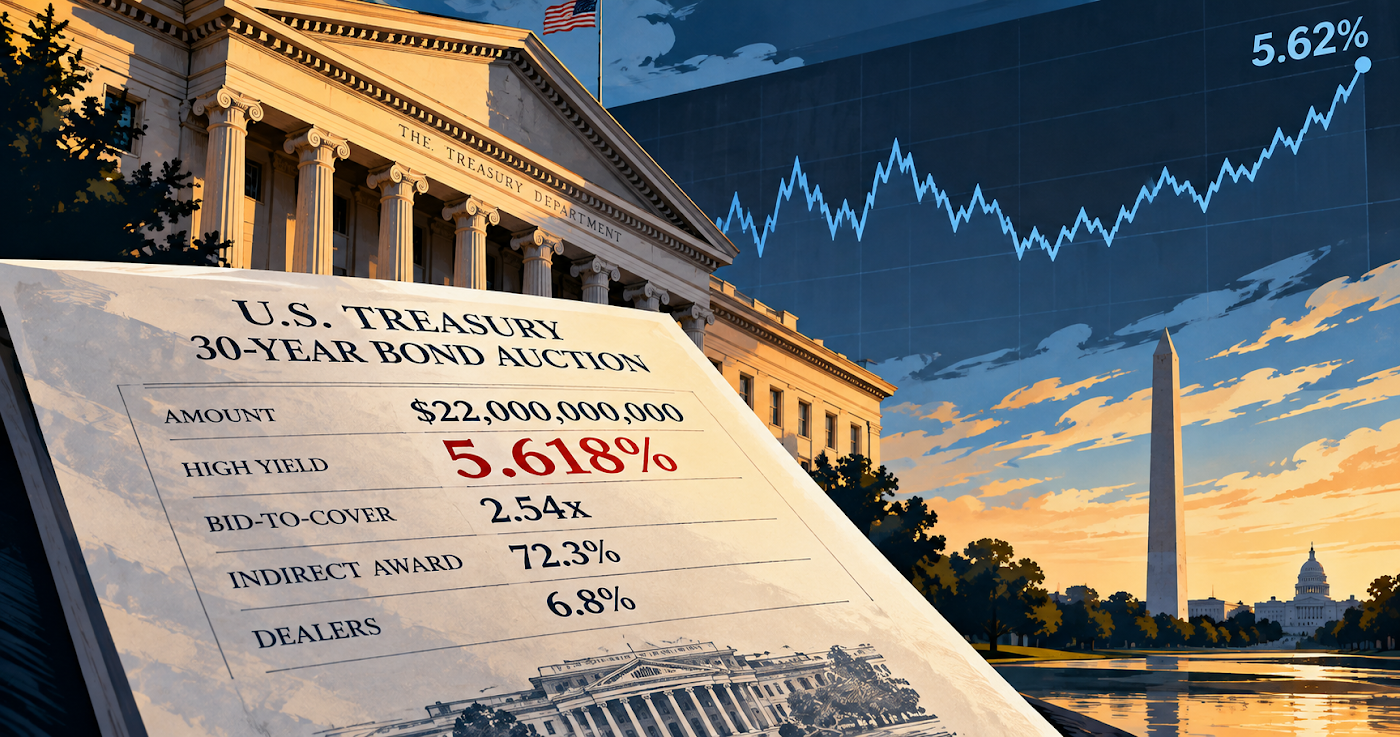
Could This Stock Be “Trump’s Next Big Buy”?Jim Rickards believes the Trump administration is about to take a direct stake in a tiny $2 stock. The Trump administration has taken a direct stake in MP Materials, Lithium America, Trilogy Metals, and USA Rare Earth. Each time, shares sprinted higher. Click here to see why Jim believes this one is next. THE LEAD SIGNAL The longest Treasury bond found buyers at an auction yield not seen in 26 years.Treasury sold $22 billion of 30-year bonds at 5.618%, the highest yield for a 30-year sale since August 2000. September's sale cleared at 5.308%. Buyers asked 31 basis points more in a month. Bids came to 2.54 times the amount on offer. That was below September's 2.61 and above the recent average of 2.41. Indirect bidders, a group that includes foreign official accounts, took 72.3%. Dealers were left with 6.8%. Wednesday's 10-year sale left dealers just 2.5%. The 30-year ended near 5.61%, down about 6 basis points on the day. The president's Iran post landed 43 minutes before the sale, so the move cannot be pinned on the auction alone. Two Sales, One Price Two long-end sales in two days cleared without leaning on dealers. That answers whether buyers exist at these yields. It does not show that yields have peaked. Buyers still demanded 31 basis points more than in September, and bids thinned from last month. September's CPI on Oct. 14 is the next test of that demand. THE ARCHITECTURE Oil got a date for U.S. restraint. It did not get an end to the risk.Brent touched $105.91 before President Trump posted that the U.S. would not attack Iran before the Nov. 3 midterms. He also wrote that the blockade "will remain in full force and effect." Brent gave back some of its gain. The other risks stayed in place. A tanker was struck north of Qatar on Wednesday. Hurricane Isaias is headed for the northern Gulf Coast. About a quarter of Gulf of Mexico oil output was shut in as of Wednesday. Heating oil rose about 5%. Energy sits first on Fed Governor Christopher Waller's list of worries. He expects more rate hikes, but said they "do not need to come at consecutive meetings." Kalshi's October hike contract traded near 15 cents after the close. Its December meeting contract last traded near 72%. A Pledge With a Date The pledge took one escalation path off the calendar until Nov. 3. Most of the oil premium stayed, along with the blockade, the attacks and the storm. That leaves energy on Waller's list of worries. Iran says its reply to U.S. proposals is days away. Isaias is due ashore late Friday or early Saturday. Both will test how much of the premium is political. FROM OUR PARTNERS Carnegie didn't invent steel. He used new technology to produce it cheaper and faster than anyone on Earth. Rockefeller didn't discover oil. He used industrial machinery to refine it more efficiently. Vanderbilt didn't build the railroad. He understood that whoever controlled the infrastructure controlled the economy. Their combined fortunes were between $700 billion and $1 trillion. Best-selling financial author Alexander Green has identified three companies positioned to be the Titans of the AI age. CLICK HERE TO FIND OUT WHO THEY BEFORE THE WINDOW CLOSES THE CROSS-CURRENTS Chips took the day's worst hit while most stocks held up.The Philadelphia semiconductor index fell about 3.4% on a day an equal-weighted S&P 500 fund edged higher. A Financial Times report put OpenAI's yearly revenue pace about $20 billion short of earlier signals. OpenAI has not publicly addressed the figure. Oracle, which supplies cloud capacity to OpenAI, closed down about 5.6%. The report landed as the build-out leans harder on credit. Broadcom is working to arrange more than $50 billion to finance its OpenAI chip, people familiar with the talks said. Oracle is in talks with Apollo and Goldman Sachs on a vehicle that would buy chips and lease them to Oracle. The Payoff Question A large share of chip buying is financed against AI revenue that has not arrived yet. Thursday raised a question about the sector's anchor customer. Because the selling stayed in AI-linked names, one reading is a revenue doubt, not a rate scare. Another is that long yields near 2002 highs still weigh on high-multiple stocks. An OpenAI response or TSMC's spending outlook later this month would show which reading holds. PARTNER SPOTLIGHT He predicted the 2008 financial crisis…He predicted Trump’s election in 2016…. He even predicted the rise of COVID-19 writing: “The chance we don’t have something on the scale of a national pandemic in the next few years is near zero” That was three months before the first reported case. If he’s right again, God Bless America… Because this crisis will be tectonic in scale…and it's going to begin with the bubble popping in AI. Click here to view his latest warning THE FORETELL LENS Thursday's contracts held their dates while other markets moved fast. The October hike contract ranged from 14 to 17 cents after Waller spoke, ending near 15. December held near 72%. The October blockade contract sat near 20 cents after a pledge that kept the blockade. Brazil's contracts held still for hours after a poll, then moved on one large block. The Patient Book Event prices moved in small steps through the day's news. Bonds and chips repriced within hours. FINAL FRAME Thursday's relief came through the bond market. It stopped short of AI.The 30-year cleared at its highest auction yield since 2000, and long yields held their decline. Oil kept most of its jump. Chips fell after a question about AI revenue. What is priced: a December hike near 72%, a U.S. announcement ending the blockade by Oct. 31 near 20%, and a Flávio Bolsonaro win near 85%. What these contracts don't capture: an answer from OpenAI, a reply from Iran, or a hot CPI. Buyers came back for the long bond. The AI trade is still waiting for its answer. Capital moves early. Coverage catches up. The gap between the two is worth watching. 3 Market Signals Most Investors Aren't WatchingThe headline is usually the last place the story shows up.
By the time everyone is talking about a stock… the signals underneath it may have been changing for weeks. • Institutional money moves. • Options activity changes. • Management confidence shifts. • Fundamentals improve, or quietly begin telling a different story. That’s exactly what our analysts found in three stocks where the evidence stopped agreeing with itself.
And in all three cases, the story is still developing. See the 3 Stocks, Get the Free Report → |