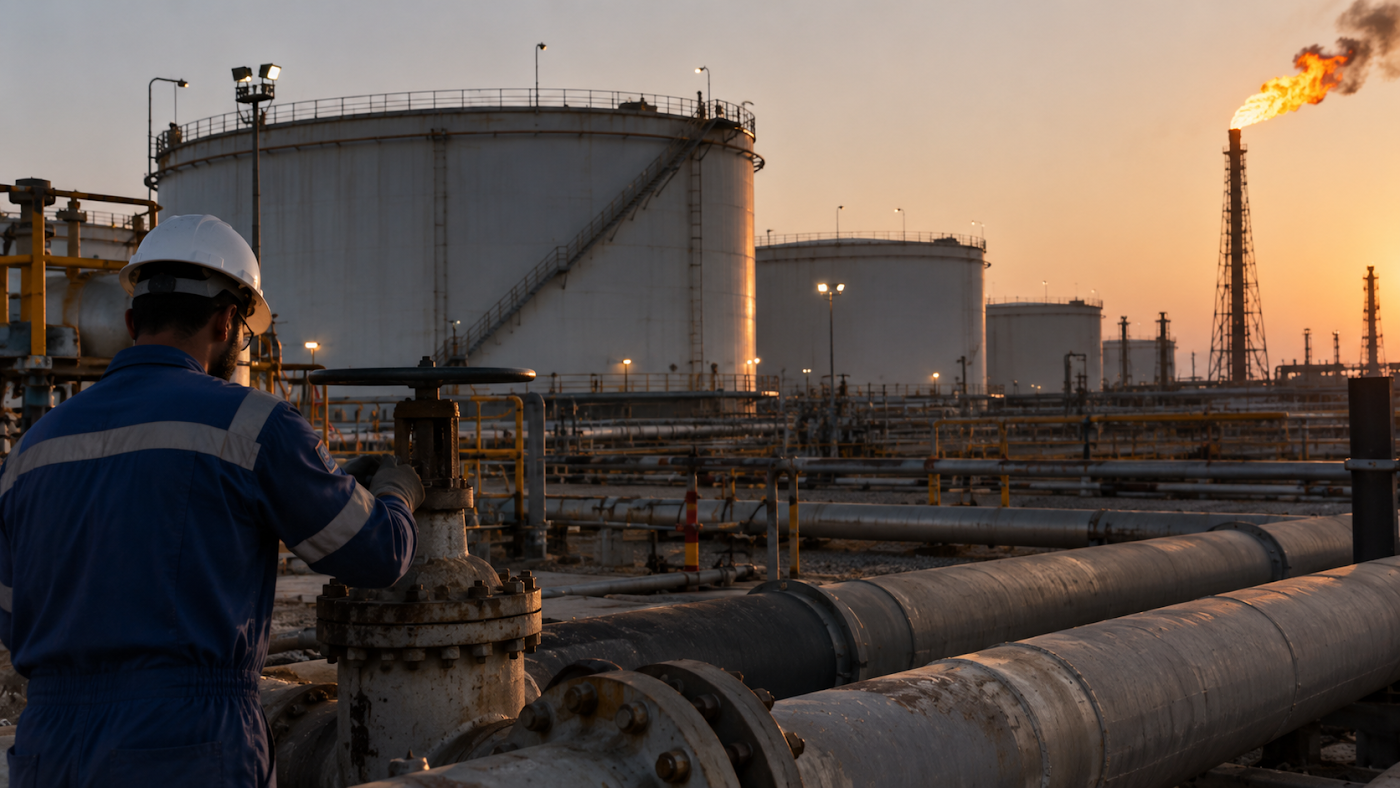
THE DAILY PULSE Thursday opens with the bond market in control.Nasdaq-100 futures fell about 1%. S&P 500 futures dropped 0.6%. Dow futures lost roughly 215 points after U.S. stock futures fell Thursday on higher yields and fresh oil pressure. The 10-year Treasury yield climbed near 5.15%. The 30-year reached about 5.44%, its highest level since 2004. The 2-year moved near 4.90%. Oil added the second pressure point. Brent traded above $105. WTI moved near $94 after hopes for a clean U.S.-Iran deal faded. That is the morning problem. The market is no longer choosing between oil risk and rate risk. It is getting both at once. Prediction markets show the same turn. Polymarket prices the 10-year hitting 5.3% before 2027 at 63%. A move to 5.4% sits at 41%. A move to 5.5% sits at 33%. October prices a 25 basis point Fed hike at 68%. December prices another hike at 72%. Traditional markets are selling the higher-rate tape. Prediction markets are mapping how far the rate and oil tails can extend. PREMIER FEATURE 7 Stocks That Could Become the Market’s Next GiantsApple, Google, Tesla… Sure, they’re household names now, but these companies and the other members of the original Magnificent 7 didn’t start out obvious. They earned their place over time. Our analysts believe the next generation of market leaders is forming now… And we’ve identified the 7 companies that fit the “Magnificent” pattern. You can see the full list for free today Don’t wait until everyone’s talking about them. Get Your Free Report Today. THE LEAD SIGNAL The lead signal is that the 10-year is no longer just a pressure point.It is the price setting for the whole tape. Wednesday’s evening letter said the bond market took control. Thursday morning confirms it. The 10-year is near 5.15%, and the 30-year is above 5.4%. That matters because every equity bounce now needs permission from the long end. The trigger was stronger data and hawkish Fed commentary. U.S. services activity rose to 58.7 and manufacturing hit 56.7, showing demand still has force. Fed Governor Michael Barr said further policy moves would likely be needed. New York Fed President John Williams said another hike by year-end would be reasonable. Prediction markets put numbers on that pressure. October sits at 68% for a 25 basis point hike. No change is 32%. December sits at 72% for a 25 basis point hike and 27% for no change. The Rate Gate Stocks can rebound from oil relief. They struggle when the discount rate rises. THE ARCHITECTURE Oil is no longer helping the bond market.Earlier this week, lower crude helped yields ease. That link broke when Brent moved back above $105 and WTI moved toward $95. The move came as oil rose on limited progress in U.S.-Iran talks and as traders kept a geopolitical premium in the barrel. The flow data is better than the headline risk. Asia imports are on track to reach 23.96 million barrels a day in September, up from 23.38 million in August and the highest since February. Middle East exporters have also expanded alternative routes around Hormuz. But the routes are costly, and Hormuz is not normal. That is why the oil tail stayed alive. Kalshi prices WTI above $115.01 by year-end at 36%. Above $120.01 sits at 31.7%. Above $125.01 sits at 24.9%. The Barrel Floor Supply is moving. The cost of moving it keeps oil risk alive. FROM OUR PARTNERS Louis: The "Strawberry Problem" Is Stalling the AI Revolution
Billion-dollar tech investor Louis Navellier calls it "AI's darkest secret." Until AI models solve the "Strawberry Problem," they'll never create new breakthroughs in medicine, energy, or quantum computing. The good news? One company is about to solve the crisis… unleashing a new $100 trillion opportunity. Click here for details. This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here. THE CROSS-CURRENTS The policy books are tightening while the relief books shrink.The diesel export-ban book shows policy pressure is not the base case yet. A U.S. diesel export ban by September 30 sits at 6%. By October 31 it sits at 22%. That matters because diesel is the link between crude, freight and household inflation. The market is not pricing a ban today. It is pricing enough stress to keep the contract alive. The trade story gives risk assets one offset. The U.S. and China agreed to extend their trade truce by two months, giving both sides more time to negotiate. That lowers one source of supply-chain pressure. But the bond market is focused on the other two. Higher oil keeps inflation risk visible. Stronger business data keeps the Fed path active. That is why futures fell even with a trade truce extension in the background. The Policy Squeeze Trade risk eased. Rate risk and fuel risk rose faster. THE FORETELL LENS Prediction markets are useful today because they show which risks are moving from near-term relief into tail pressure.The Fed book shows the policy tail. October at 68% and December at 72% say traders are not treating last week’s hike as a one-off. The Treasury book shows the rate tail. A 5.3% 10-year before 2027 sits at 63%. A 5.4% touch sits at 41%. A 5.5% touch sits at 33%. The oil book shows the energy tail. WTI above $115.01 by year-end sits at 36%, with $120.01 at 31.7% and $125.01 at 24.9%. The CFTC added a rulebook tail too. It warned that mention-market contracts carry a higher manipulation risk because settlement can depend on what a specific person says or does. The agency pointed to safeguards around public settings, independent verification and surveillance. That matters because prediction markets are moving into bigger financial questions while regulators are drawing tighter lines around sensitive contract types. The Tail Stack The market is not pricing one shock. It is pricing several extensions. PARTNER SPOTLIGHT 15X Bigger Than SpaceX: Elon's New Launch
While the rest of the market goes crazy for "the mother of all IPOs", a new Elon Musk innovation is quietly being rolled out nationwide. It's been 27 years in the making, and it could have a radical impact on how millions of people manage their money… and even collect Social Security. Here's everything you need to know. This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here. FINAL FRAME Thursday begins where Wednesday closed.The relief trade broke. The 10-year moved higher. Oil rebounded. Fed odds tightened. Stocks turned lower before the open. What is priced: a 68% chance of an October hike, a 72% chance of a December hike, a 63% chance the 10-year touches 5.3%, a 36% chance WTI clears $115.01 by year-end, and a 22% chance of a diesel export ban by October 31. What is not priced: the 10-year holding above 5.15%, the 30-year staying near 2004 highs, WTI moving back toward $100, diesel stress becoming policy, or CFTC guidance slowing the mention markets. The market wanted relief. The bond market demanded restraint. Capital moves early. Coverage catches up. The gap between the two is worth watching. 3 Stocks at a Major Turning PointSomething unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else. That kind of disagreement can matter. Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch. Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next. Get the Free Report: 3 Stocks at a Major Turning Point → | 


